
Retire in style
While you should effectively take advantage of the benefit of compound interest while retirement is still far off, there are many other factors to be aware of when planning your retirement. It is also vital you choose the right savings vehicle to suit your needs.

When investing for retirement, it is important to plan for future increases in prices and future increases in your standard of living. Price inflation is a general increase in prices and a corresponding fall in the purchasing power of your money.
Lifestyle
Salary increases that keep pace with price inflation allow you to maintain a fixed standard of living over time. However, salary increases that exceed price inflation may increase your standard of living and therefore your cost of living. You can think of this as ‘lifestyle inflation’, which is the increase in your standard of living over time.
As you become accustomed to a certain lifestyle, you will need to increase your retirement savings to maintain this stand-ard of living, or otherwise risk spending far beyond what your retirement savings will allow.
Volatility
Another factor you need to keep in mind is market volatility – this can affect the longevity of your savings. While market
volatility is to be expected (it is a normal part of investing) it is something you need to take into account and effectively combat to ensure optimal performance of your retirement vehicle.
Risky business
To achieve above-inflation [real] returns, you need to be comfortable taking on some risk. History has shown that over the long term, equities provide the best return. While returns do not come in a straight line, fluctuations smooth out over time. If you invest in equities, you need to be comfortable with a bumpy ride.
Spreading your risk by investing in various sectors and industries will ensure that you are adequately equipped to tackle market volatility.
Market conditions in general have an impact on all investments including retire-ment savings. Inflation will contribute to your income goal increasing over time and market volatility will affect the value of your savings and, as a result, the benefit that this can produce.
Having said that, this is not necessarily a bad thing – consider a person who only
invests in cash, where volatility is very low. He / she will probably have a worse outcome over the long term, compared with a person in a portfolio that can produce returns above inflation even if the portfolio is volatile.
Bear in mind that investment returns are a net result of asset allocation (your choice of assets) less fees. You need to ensure your savings vehicles are cost-effective, completely transparent and reviewed regularly, with a clear indication of contributions, costs and returns.
Timing
It’s never too late to save (although being 60 with no retirement plan would probably constitute “too late”) so ensure your financial independence during retirement by starting today. Do this by consulting a financial adviser and looking into savings vehicles.
Through careful planning and the allocation of your capital into diverse assets, you can achieve a comfortable retirement. Savings are not only the fixed debit-order or employment -based retirement plan you sign up for, but also the assets you acquire, like property and equities, along the way. The combination of these plus personal savings and employment-based savings should be focused collectively to generate this exact result [a comfortable retirement].”
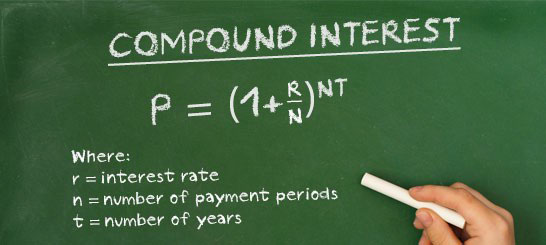
The power of compound interest
The longer you delay to starting your savings plan, the more you are going to have to save. Using a basic future value calculation, we can compare two 20-year-olds who wish to retire at the age of 60. Client A saves R1 000 a month from the age of 20 to the age of 30. He then stops contributing but leaves the funds invested until he reaches 60. Client B, on the other hand, saves R1 000 from the age of 30 until he retires at 60.
Assuming a growth rate of 10% for both A and B the results are as follows: Client A will have saved a total of R1 000 x 12 months x 10 years = R120 000. Client B will have saved R1 000 x 12 x 30 years = R360 000. At the age of 60, Client A will have capital valued at R4m, whereas client B will have only R2.3m. This shows the cost of delay.