Life is for the living
A lot of attention and financial writing focusses on the preparation and saving for retirement. However, what happens when you retire, how you manage your resources, is just as important for a comfortable and sustainable period in one’s life. Making it a little more difficult to navigate are all the financial terms and jargon. Words like annuities, blended options, drawdown and escalation rates all make navigating the golden years stressful and sometimes confusing. One of the most important decisions one has to make is whether a Life, Living or Blended annuity best suits your needs.
Retirement is not the end of the road. It is the beginning of the open highway. However, freedom has a price and in this case that price requires some careful decision making. When you approach retirement, you will need to decide whether to invest the two-thirds of your pension fund or retirement annuity in a living or a life annuity. But with so many financial service providers offering a host of life, living and hybrid annuity products, it may be difficult to know which annuity product gives you the best possible retirement income that is suited to your individual circumstances.
Life Annuities
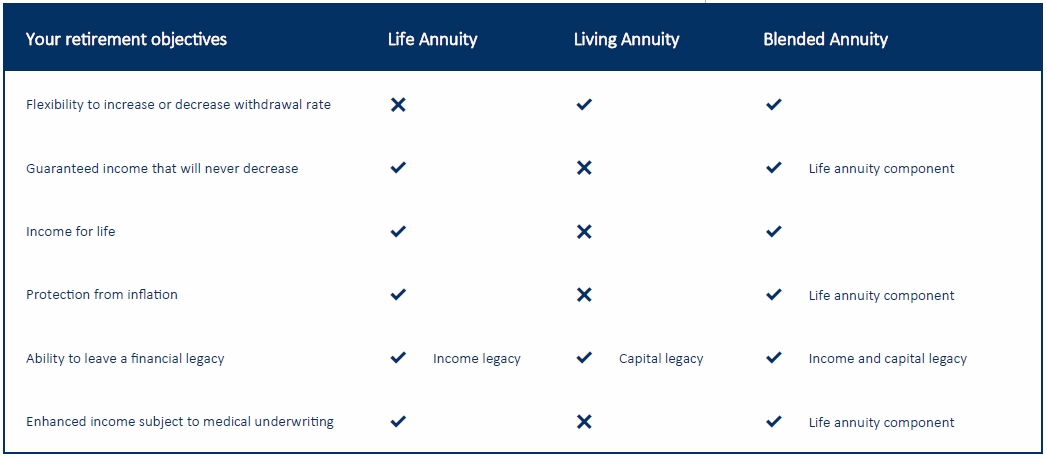
Traditional life annuities are designed to offer pensioners security by providing a guaranteed income for life that never decreases. They are available in two basic forms: with-profit annuities, and non-profit annuities. With-profit annuities have an underlying investment component that determines their increase potential. Non-profit annuities, such
Life Annuities
Traditional life annuities are designed to offer pensioners security by providing a guaranteed income for life that never decreases. They are available in two basic forms: with-profit annuities, and non-profit annuities. With-profit annuities have an underlying investment component that determines their increase potential. Non-profit annuities, such
as inflation-linked or fixed escalation annuities, provide a guaranteed in-crease either equal to inflation or to the selected fixed escalation rate.
Living Annuities
If you are looking for the flexibility to ad-just your annual drawdown rate (and thus your monthly income amount) to match changing income needs, living annuities offer a more flexible option, allowing drawdown rate adjustments every year of between 2.5 and 17.5%.
The risk associated with living annuities is that they do not guarantee a retirement income for life, and there is a chance that you may eat into your capital too quickly – especially during times of poor market performance. This means that you may run out of money before you die.
Income Legacy
Both life and living annuities allow you to leave a financial legacy. Any remaining balance from a living annuity is automatically passed on to beneficiaries, whereas
Living Annuities
If you are looking for the flexibility to ad-just your annual drawdown rate (and thus your monthly income amount) to match changing income needs, living annuities offer a more flexible option, allowing drawdown rate adjustments every year of between 2.5 and 17.5%.
The risk associated with living annuities is that they do not guarantee a retirement income for life, and there is a chance that you may eat into your capital too quickly – especially during times of poor market performance. This means that you may run out of money before you die.
Income Legacy
Both life and living annuities allow you to leave a financial legacy. Any remaining balance from a living annuity is automatically passed on to beneficiaries, whereas

in a life annuity, you can opt to include additional income legacy features to provide for your spouse and family in the event of your early death.
A Blended Retirement Option
One way to combine the best of both living annuities and life annuities and overcome their disadvantages is to use both. At retirement, current regulations allow retirees to split part of their pre-retirement savings between multiple living annuity and/or life annuity products, with one or multiple insurers.
A unique legal structure, a blended annuity enables you as the annuity holder to include a guaranteed life annuity as one of the investment portfolios within a living annuity.
A Blended Retirement Option
One way to combine the best of both living annuities and life annuities and overcome their disadvantages is to use both. At retirement, current regulations allow retirees to split part of their pre-retirement savings between multiple living annuity and/or life annuity products, with one or multiple insurers.
A unique legal structure, a blended annuity enables you as the annuity holder to include a guaranteed life annuity as one of the investment portfolios within a living annuity.
By purchasing a blended annuity, you can weigh up your wants and needs, then decide how much to allocate to the guaranteed component and how much remains flexible. Blending also allows you to optimise your income over time, balancing the risk of outliving your savings by adding to the guaranteed component when required.
Conclusion
Many people wish to spend most or all of the money they’ve worked so hard to earn and invest during their lifetimes. Others want to make sure they leave an inheritance for their spouse, children or charities they support.
Make that decision and you will have the answer.
Conclusion
Many people wish to spend most or all of the money they’ve worked so hard to earn and invest during their lifetimes. Others want to make sure they leave an inheritance for their spouse, children or charities they support.
Make that decision and you will have the answer.